Work

10+ years of pricing risk with data

From forecasting and drug repurposing at Wipro, to credit and surety at Swiss Re, to leading AI for credit reinsurance at Marsh Re.

Experience

2025 to present
London

SVP, Credit Reinsurance AI

Marsh Re (formerly Guy Carpenter)
  • Leads data and AI for Credit, Bond and Political Risk, with a focus on actuarial pricing in credit reinsurance.
  • Builds on Databricks across pricing, risk and portfolio workflows.
  • Develops LLM products for pricing support, entity matching, data transformation, wording analytics with RAG, contract management, workboard automation, email analytics and bordereaux management.
  • Databricks
  • PySpark
  • LLMs
  • RAG
  • Agentic systems
2020 to 2025
London

Lead Data Scientist and Product Owner, Credit & Surety

Swiss Re
  • Owned the end-to-end data and AI landscape for Credit & Surety on Palantir Foundry.
  • Worked with Prof. Dimitris Bertsimas (MIT) on contract bond default prediction using optimal classification trees.
  • Built underwriting memo generation and document summarisation with generative AI.
  • Delivered £400k in IT cost savings through Palantir Foundry, and released 2 FTE by automating bordereaux reporting.
  • Palantir Foundry
  • Palantir AIP
  • PyTorch
  • FinBERT
  • Azure ML
2016 to 2020
Bangalore

Data Science Manager, Advanced AI Practice

Wipro
  • Built sales prediction models for major clients, including Levi’s forecasting work presented by the CFO at the World Economic Forum in Davos.
  • Led a COVID-19 drug repurposing AI programme in partnership with Stanford University, later continued by the Government of India.
  • Drove high-accuracy time-series forecasting for revenue and cost strategy.
  • PySpark
  • XGBoost
  • AWS SageMaker
  • GCP
  • IBM Watson

Independent work

Projects

Apps built outside the day job: a creative studio for seeing risk differently, a private record-matching tool, and pricing engines applying hazard, vulnerability and portfolio-capital thinking to different kinds of risk.

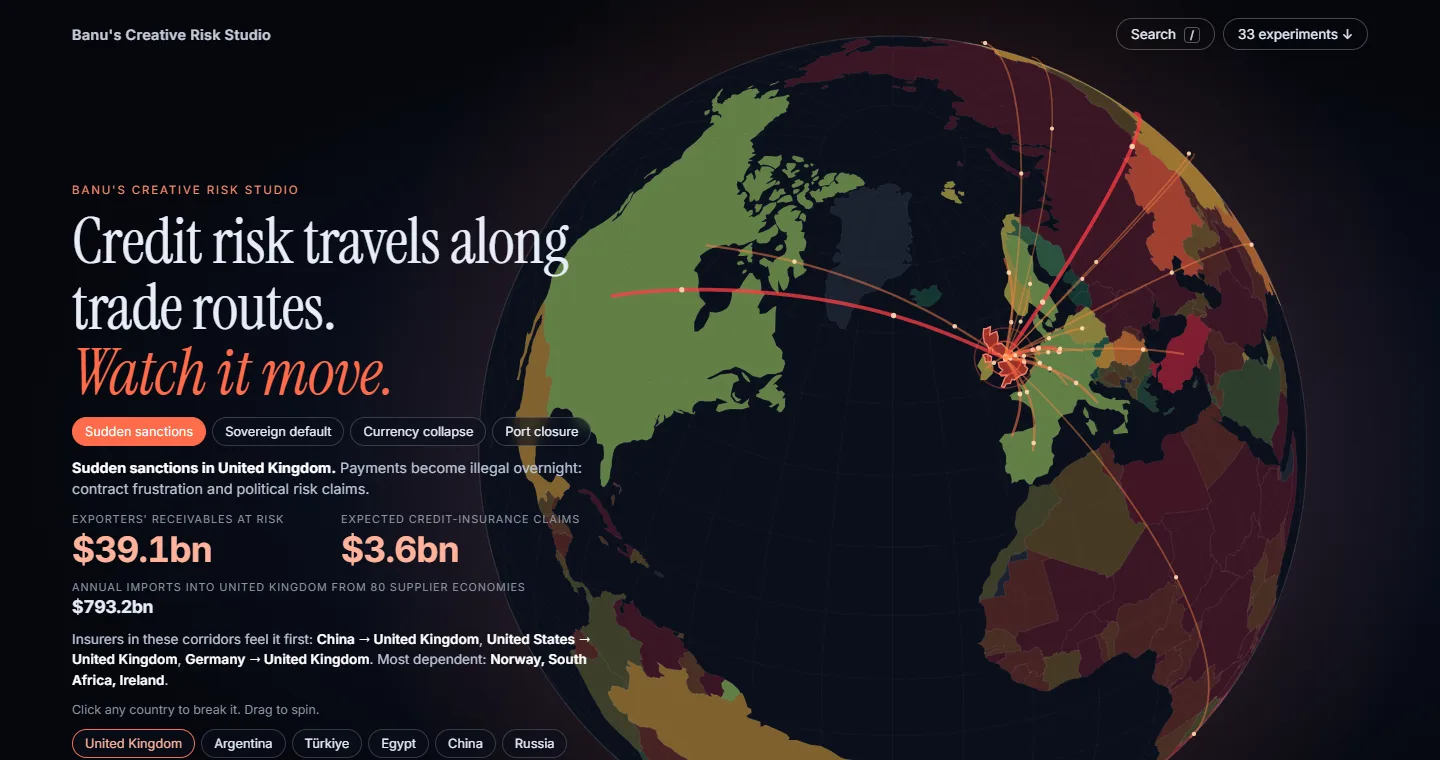
Creative Risk Studio front page: the Contagion Globe showing credit risk travelling along trade routes
Live Creative work

Creative Risk Studio

Risk isn’t a number, it’s a chain reaction. A growing collection of experiments for seeing it that way: break a country on the Contagion Globe and watch credit risk travel along real trade routes, play your way through the maths, replay a crisis, or simply ask the studio’s AI a question out loud.

  • Svelte
  • TypeScript
  • Vite
  • D3 globe
  • Live public data

Personal project, built in my own time. Uses public data such as USGS, GDACS, NASA, the World Bank, FRED and UN Comtrade; shock probabilities and pricing loads are illustrative. Not affiliated with my employer.

  • Contagion Globe: pick a shock, such as sudden sanctions or a sovereign default, and see receivables at risk and expected credit-insurance claims ripple along real trade links
  • Games that teach: a Quant Arcade from gambler’s ruin to Black-Scholes, Merton and Markov rating migration, plus role-play games like Be the Reinsurer and Renewal Day
  • A quant course from roulette to Markowitz, and an efficient frontier for a reinsurer’s lines of business
  • Crisis replays and cascades: Suez, COVID and 2008, shock chains with probability, delay and cost on every link
  • Ask Banu, a spoken AI assistant, plus live hazards, credit markets and Voyager 2 tracked live from NASA
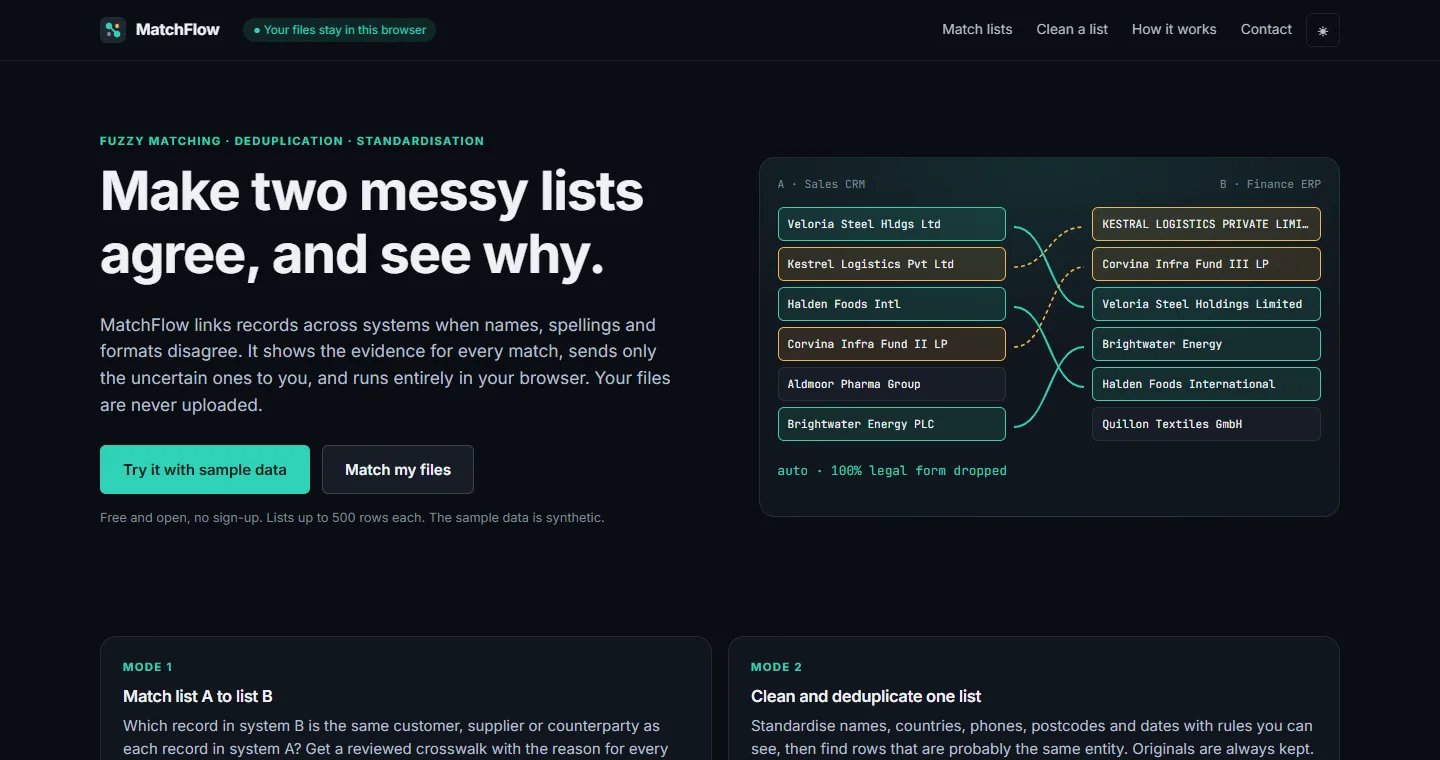
MatchFlow home screen matching messy company names between a sales CRM and a finance ERP
Live Private by design

MatchFlow

Company name matching, done properly. Make two messy lists agree, and see why: MatchFlow links records across systems when names, spellings and formats disagree, such as “Veloria Steel Hldgs Ltd” in a CRM and “VELORIA STEEL HOLDINGS LIMITED” in an ERP. Clear matches link themselves, uncertain ones queue for a person with the evidence laid out, and nothing is ever uploaded.

  • React
  • TypeScript
  • Web Workers
  • Vite
  • FastAPI

Personal project, built in my own time on published record-linkage methods. Free and open for lists up to 500 rows; the sample data is synthetic. Not affiliated with my employer.

  • Two modes: match list A to list B into a reviewed crosswalk, or standardise and deduplicate a single list
  • Explainable: per-field evidence, Fellegi-Sunter style weights, named penalties for contradictions such as a different country or “Fund II vs Fund III”, and the margin over the runner-up
  • Private: files are read and matched in Web Workers in your browser, so no row ever reaches a server
  • Measured: on its synthetic answer key, 251 of 251 automatic links are correct and every true match is surfaced
  • Built to scale: blocking scores about 0.7% of the 26 million possible pairs in a 5,000 by 5,000 benchmark
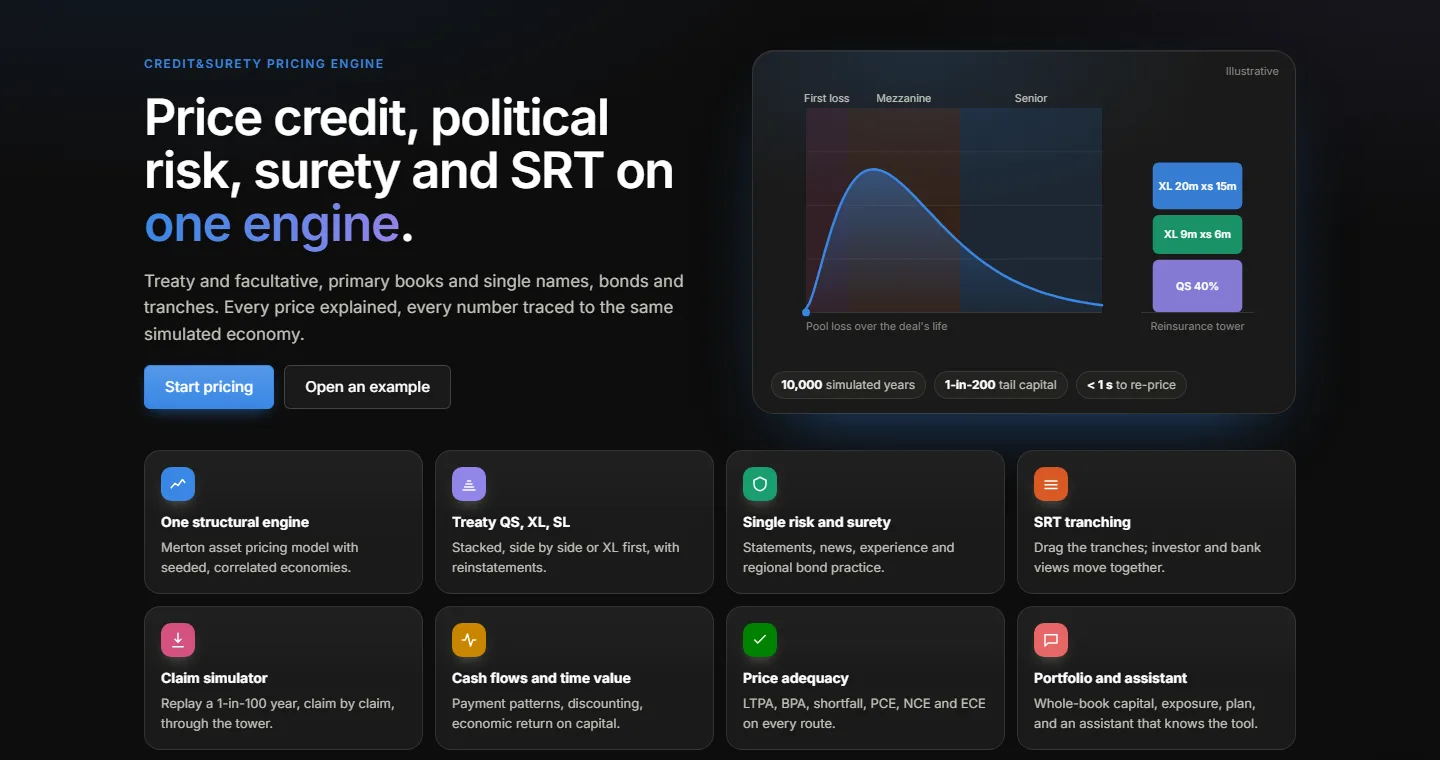
Credit & Surety Pricing Engine home screen, showing a loss distribution and a reinsurance tower
Live

Credit & Surety Pricing Engine

Prices credit, political risk, surety and SRT on one structural engine. Treaty and facultative, whole books and single names, bonds and tranches, with every price explained and traced back to the same simulated economy.

  • Python
  • FastAPI
  • NumPy & SciPy
  • React
  • TypeScript

Personal project, built in my own time on open, published methods. Synthetic books and fictional names only. Not affiliated with my employer.

  • Treaty pricing for quota share, excess of loss and stop loss, stacked or side by side, with reinstatements
  • Single risk credit and surety bonds, priced on their own and against the book
  • SRT tranche pricing, with the investor and bank views moving together
  • Merton asset model with seeded, correlated economies, 10,000 simulated years and 1-in-200 tail capital
  • Claim simulator, cash flows, price adequacy and a built-in pricing assistant
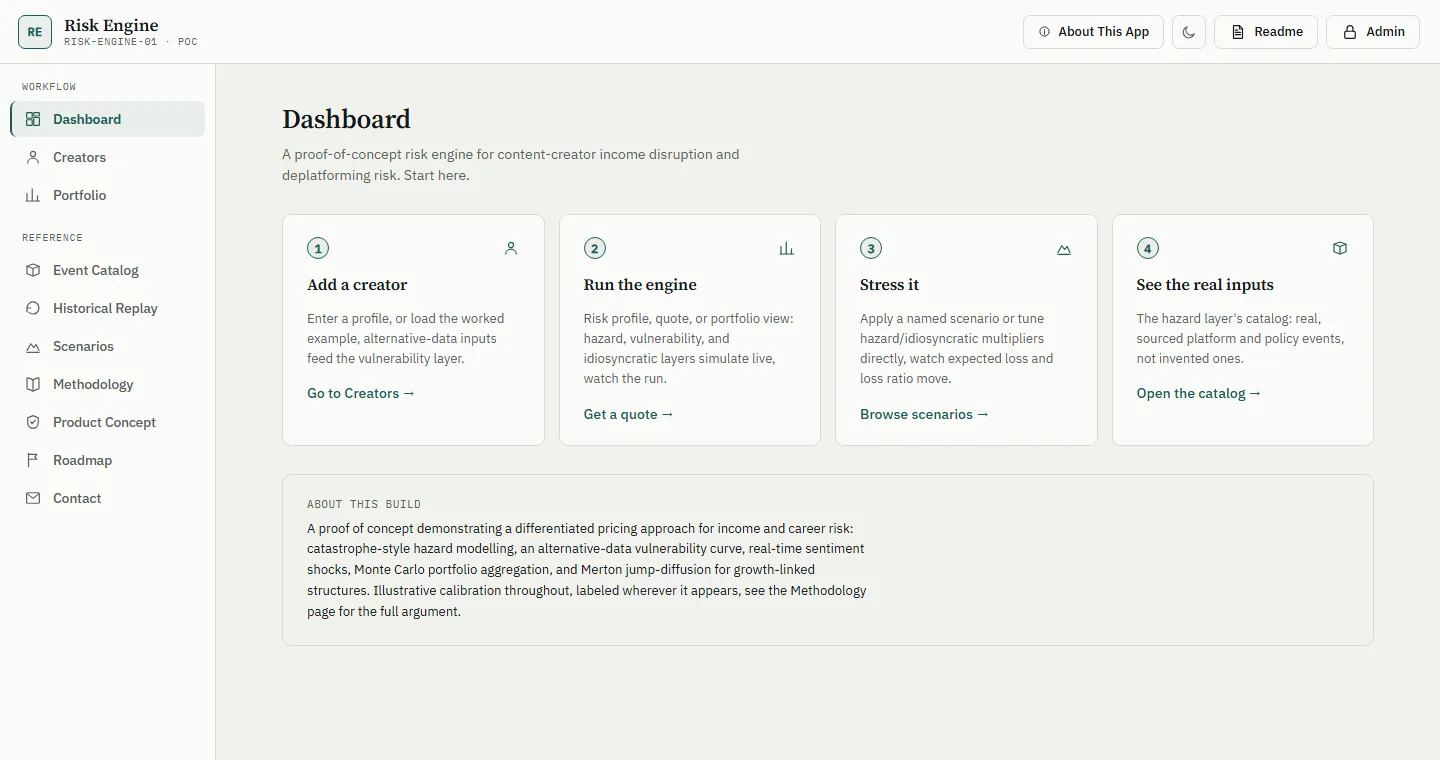
Influencer Risk Engine dashboard, showing the four-step workflow from creator profile to stress testing
Live · proof of concept First of its kind

Influencer Risk Engine

The first quantitative pricing engine for creator income risk. Deplatforming, algorithm shocks and scandals can wipe out a creator’s income overnight, yet no insurer prices that risk quantitatively today. This engine does, by borrowing the machinery of catastrophe reinsurance.

  • Python
  • FastAPI
  • NumPy & SciPy
  • GARCH
  • Regime switching
  • React

Personal proof of concept, built in my own time on open, published methods. Illustrative calibration, labelled in the app. Not affiliated with my employer.

  • Hazard layer: catastrophe-style modelling of platform algorithm changes, policy shifts and ad-market shocks, from a maintained event catalogue
  • Vulnerability layer: a per-creator exposure curve from alternative data, such as platform concentration, niche, audience quality and revenue diversification
  • Idiosyncratic layer: real-time NLP on sentiment and sentiment velocity for scandal and personal-event shocks
  • Portfolio and capital: Monte Carlo loss distributions, expected loss, EVT-fitted VaR and CVaR, economic capital and RAROC
  • Optionality: Merton jump-diffusion for pricing growth-linked structures

Skills

Risk & pricing

  • Credit risk
  • PD / LGD / EAD
  • Basel III
  • Reinsurance pricing
  • Credit & surety
  • Political risk
  • Portfolio optimisation
  • Stochastic modelling

AI & modelling

  • Generative AI
  • LLM systems
  • RAG
  • Agentic workflows
  • NLP
  • PyTorch
  • TensorFlow
  • Bayesian methods
  • Time series

Platforms & code

  • Python
  • PySpark
  • SQL
  • TypeScript
  • Databricks
  • Palantir Foundry
  • Azure ML
  • AWS SageMaker
  • FastAPI
  • Django

Recognition

  • NASSCOM AI GameChanger AwardCOVID-19 drug repurposing research
  • Best Employee of the YearSwiss Re
  • Pinnacle AwardRecognition
  • Frontline Manager AwardRecognition
  • Guest lectureSCMHRD, Symbiosis, Pune, 2022

Education

  • B.Tech, Civil EngineeringNIT Warangal, 2012 to 2016
  • First Class with DistinctionMerit Scholar

Want to talk about a role or a project?

The quickest way to reach me is email. I reply to every serious message.